

Leopold Aschenbrenner was hailed by many as a genius after publishing a prescient and provocative essay on the trajectory of artificial intelligence. He then put that conviction to work, launching an investment firm that loaded up on highly leveraged positions tied to the AI boom.
The results were spectacular: returns skyrocketed before ultimately tanking. Is Aschenbrenner an investing genius who saw the future more clearly than everyone else, a lucky fool who made an enormous bet at exactly the right moment, or something in between? Distinguishing skill from luck is one of investing’s hardest problems.
What This Means:
-
A winning decision and a good decision are not always the same thing. Former professional poker player Annie Duke explains that a great decision that can be expected to produce a good outcome 80% of the time can still lose.1 A strong decision improves the odds without guaranteeing the result.
-
Skill and luck are difficult to separate. Outcomes usually reflect a combination of both. Returns alone rarely tell us whether a manager possesses genuine skill; strong performance only evidences skill when it continues for an extended period and endures through different regimes.
-
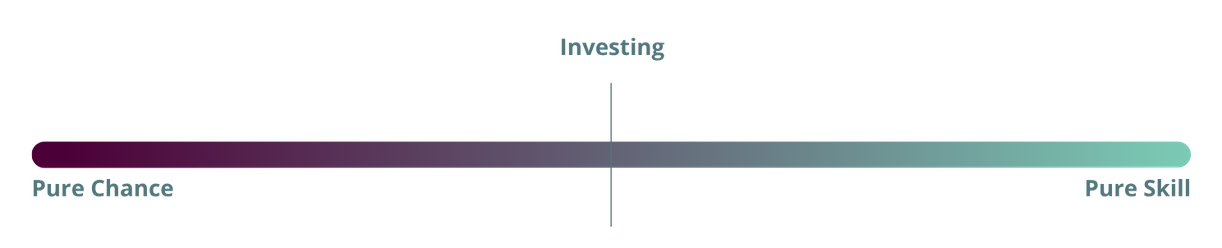
Investing falls in the middle of the skill-luck continuum. Michael Mauboussin explains that activities range from those governed almost entirely by chance, like a coin toss, to those where a skilled participant wins consistently, like Roger Federer in his prime.2 Investing sits somewhere in-between: research, judgment, and experience matter, but luck can still exert a significant influence, especially over short time periods.
Why This Matters:
-
Short-term results tell you very little. Because investing involves luck, one year of results offers limited evidence of skill. It’s helpful to assess skill across different market environments. When market leadership changes, we get a better sense of whether success came from a repeatable process or a prolonged tailwind.
-
The longer a streak runs, the harder it is to call it luck. Bill Miller outperformed the S&P 500 for a record-setting 15 consecutive years, from 1991 through 2005, spanning the tech bubble and its aftermath. Michael Mauboussin calculated the odds of that streak occurring by chance at 1 in 2.3 million.3
-
A good process can still produce a bad outcome, and vice versa. It’s important to evaluate decisions based on the information available at the time, not just the result. Even the best stock pickers are only right 50%-60% of the time.
How We’re Thinking About It:
-
We weigh what could happen, not just what we expect to happen. A sound investment process considers the full range of potential outcomes and whether the potential reward justifies the risk being taken.
-
We ask whether the edge is real and repeatable. Is the process sound? What is the investment edge, and how easily could it be competed away? Can the manager and process adapt as market conditions change?
-
We give sound decisions time to play out. A manager must be willing to recognize mistakes, learn from them, and remain committed to a sound process even when short-term results are disappointing. Over time, that combination helps make the distinction between skill and luck clearer.
Investing has a way of eventually exposing the difference between a good outcome and a good process. In the short run, luck can make almost anyone look brilliant, or foolish. Over the long run, process, adaptability, and judgment have a much better chance to reveal themselves. Time and patience are the ultimate arbiters.